The $5m+ pathway · For global investors
New Zealand's golden visa: residency, and now the home to go with it.
Here's the deal. Invest NZ$5m or more into New Zealand through the Active Investor Plus visa and you get residency. Since March 2026 you also get the right to buy or build one home worth more than NZ$5m. For the first time since the 2018 ban, serious offshore money has a legal route to both a life in New Zealand and a New Zealand front door.
How does the Active Investor Plus visa work?
It swaps investment for residency. Since its 2025 revamp it runs on two settings.
- The growth route. Around NZ$5m, committed for roughly three years, into higher-engagement New Zealand investments like managed funds and direct stakes in NZ businesses.
- The balanced route. More money, around NZ$10m over five years, in exchange for a wider and more passive menu of assets.
You'll need to meet character and health requirements, and spend a modest number of days in the country across the investment period. Your partner and dependent children are generally included.
The exact settings move with policy. That's why we describe the shape and link to the source. The current criteria live at Immigration New Zealand, and the application itself belongs with a licensed adviser. What never changes: capital in, residency out, family included.
What changed in March 2026?
An amendment to the Overseas Investment Act gave Active Investor Plus holders (and legacy Investor 1 and 2 visa holders) a streamlined consent pathway to buy or build one residential property worth more than NZ$5m. For a build, the land and construction cost together have to clear the bar.
Before that, the rules produced an odd result. You could be granted residency for investing millions here and still not be allowed to buy a house to live in. That's now fixed, and it changed the maths for families comparing one investment-migration country with another.
Is there a catch?
Two things to plan around.
First, the NZ$5m home sits on top of the qualifying investment, not inside it. So budget for both.
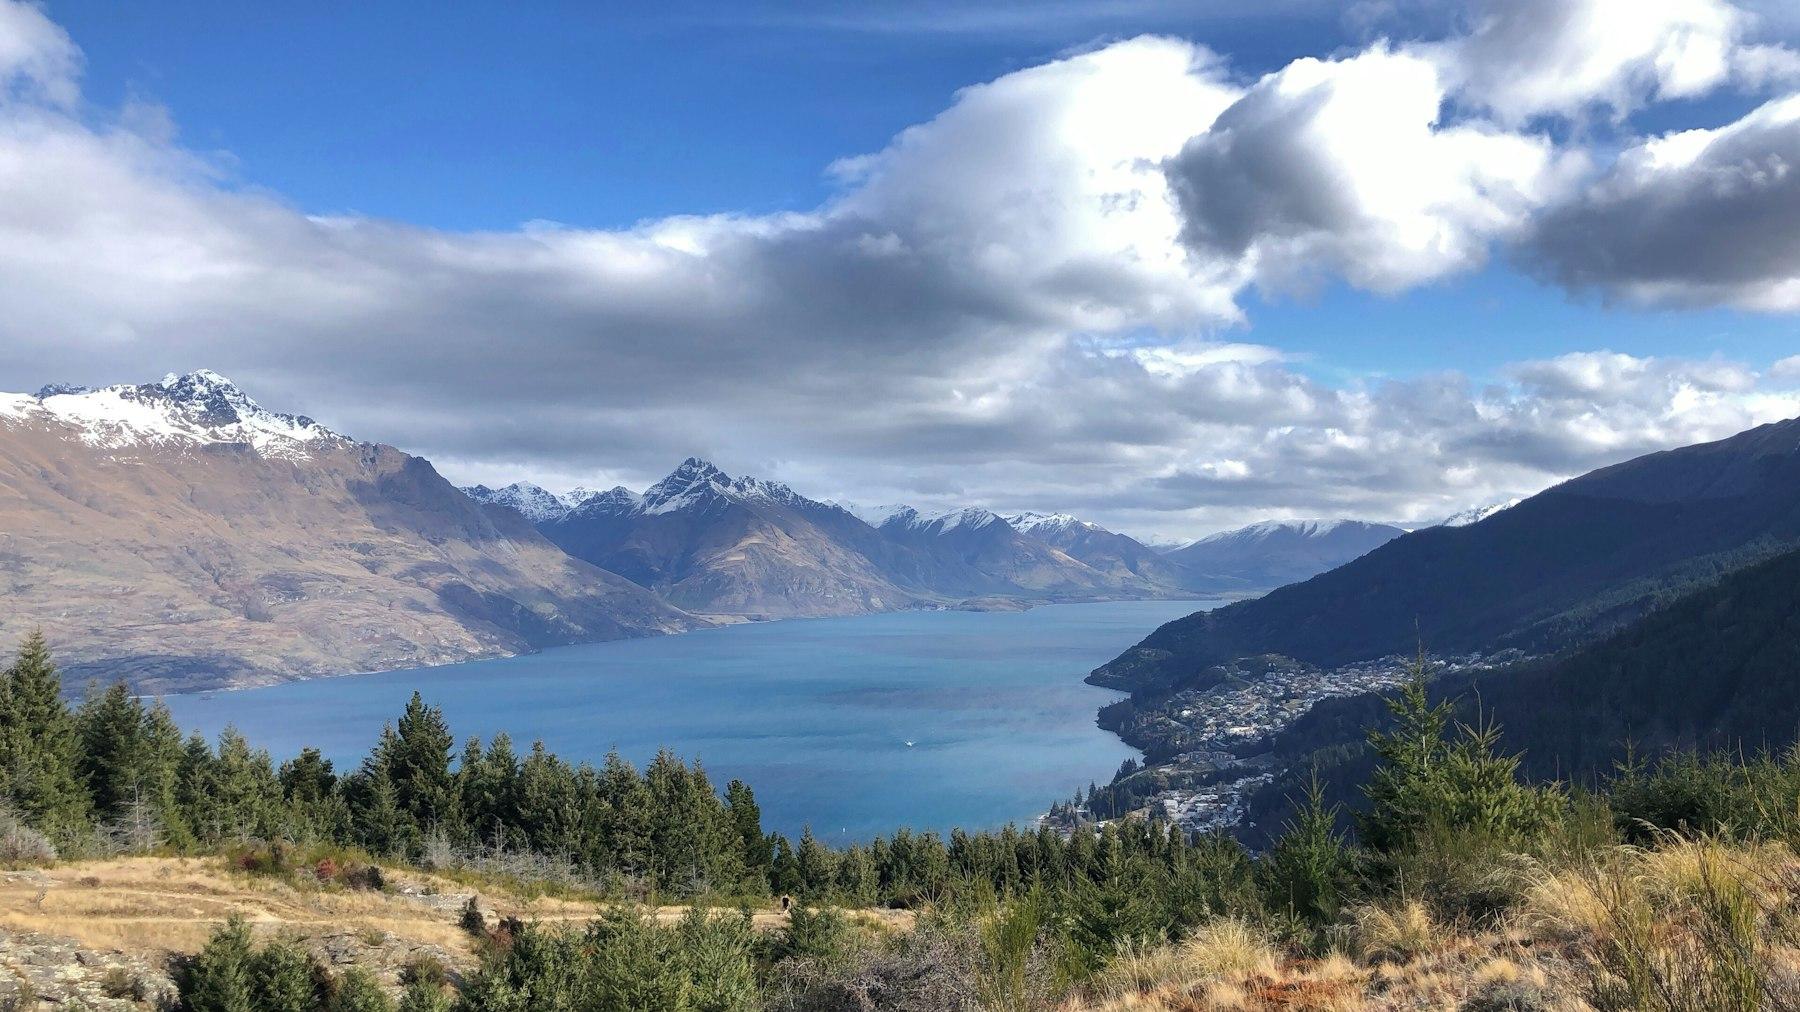
Second, only around 0.4% of New Zealand's housing stock clears the NZ$5m bar. The eligible market is genuinely the top shelf: lakefront Queenstown and Wanaka, Waiheke Island, Auckland's premium suburbs, Omaha's beachfront. The shelf is thin and the best addresses are a sellers' market, so a buyer's agent earns their keep here.
NZ$5m+
The growth-weighted investment route - roughly three years in higher-engagement NZ assets
0.4%
of NZ homes clear the $5m bar - the eligible market is genuinely the top shelf
~4 yrs
The transitional tax exemption shielding most foreign income for new tax residents
How will I be taxed once I move?
Gently, at first. That's New Zealand's quiet advantage over rival programmes.
Most new tax residents qualify for a transitional residency exemption. It shields most foreign-sourced income (dividends, interest, rents from offshore portfolios) from New Zealand tax for roughly your first four years.
Add the structural settings: no general capital gains tax, no stamp duty, no land tax, no inheritance tax. The fiscal landing is about as soft as the developed world offers.
Wealth at this scale runs on professional advice as a matter of course. Here, that advice tends to come back with good news.
Why New Zealand over the alternatives?
Against the world's other investment-migration programmes, New Zealand's offer is lifestyle-heavy and politically stable. A common-law country. Top-tier schooling. Clean air and water at scale. Direct flights through Auckland and Queenstown. And real distance from the world's troubles, which for most of our readers is the whole point.
The trade-offs are the obvious ones. That same distance. A small domestic market for the qualifying investments. And a trophy-home shelf thin enough that the right property can take patience.
If you're Australian, you need none of this. Your passport already buys here freely: can Australians buy property in New Zealand?
- 1
Scope it with licensed advice
Month 0-1A Licensed Immigration Adviser or NZ immigration lawyer tests eligibility and route choice (growth vs balanced). Verify any adviser on the IAA register first.
- 2
Application + approval in principle
Months 1-6Character, health, source-of-wealth evidence. Approval in principle starts the investment clock.
- 3
Deploy the qualifying investment
Per approvalNZ$5m+ into approved assets within the required window, held for the route's term, with modest NZ presence across it.
- 4
Residency
On conditions metResidence visa conditions progressively satisfied; family included throughout.
- 5
The home
From March 2026 rulesOne residential property above NZ$5m via the streamlined consent - buy or build, with the purchase itself running on the standard rails our how-to guide covers.
What does Slice do, and what don't we do?
Immigration advice is a licensed profession in New Zealand. Formal advice on a visa application can only come from a Licensed Immigration Adviser or an NZ lawyer, and the IAA register verifies every one of them in thirty seconds.
We're a publication. We explain the pathway, cover the property at the NZ$5m+ end, and introduce serious enquirers to the licensed advisers, buyer's agents and private-banking contacts who actually do the work. Tell us where you're at and we'll point you to the right people.